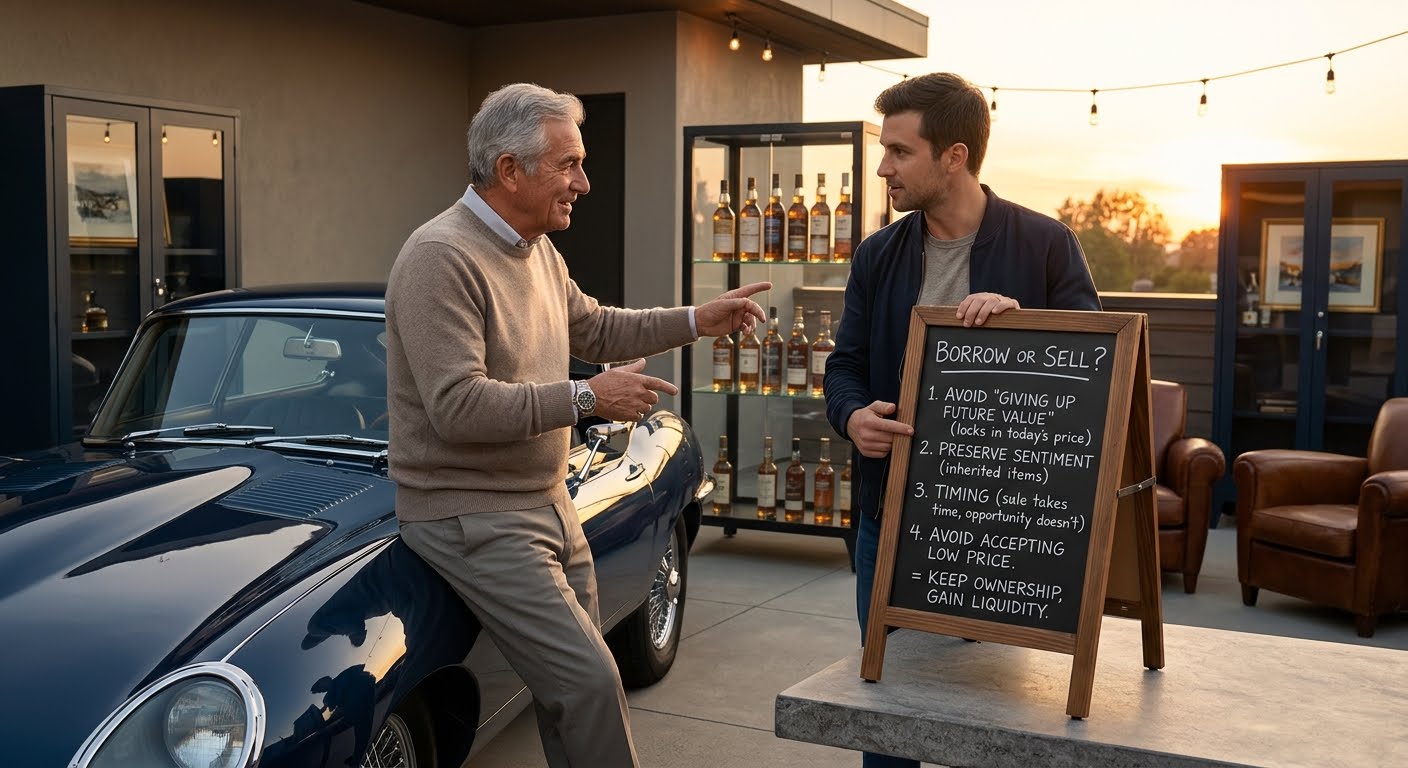
It can sound strange at first: someone owns a valuable watch, a classic car, a collection of rare whisky or perhaps even several high-value assets, yet still chooses to borrow money. Why not simply sell something and use the cash?
The answer is that wealth and available cash are not the same thing. A person can own assets worth a considerable amount while having relatively little money sitting unused in a bank account. Selling one of those assets may solve a short-term cash need, but it also means giving up something that may have investment potential, sentimental value or future usefulness.
That is why borrowing can sometimes be more attractive than selling, particularly when the need for money is temporary.
Valuable Does Not Mean Liquid
Liquidity simply describes how easily something can be turned into spendable cash.
Money in a current account is highly liquid because it can be used immediately. A valuable painting, vintage vehicle or luxury watch is different. It may be worth tens of thousands of pounds, but that value remains locked inside the asset until it is sold or used in some other financial arrangement.
This can create situations where somebody appears wealthy on paper while still needing short-term access to capital.
Specialist lenders such as Edinburgh Asset Finance operate in this space by allowing certain high-value assets to be used as security against short-term borrowing. Instead of selling the asset permanently, the owner may be able to release some of its value temporarily and recover it once the agreed loan has been repaid.
The principle is not particularly unusual. Mortgages work on a similar broad concept, with property acting as security. The difference is that specialist asset-backed finance can involve objects such as watches, jewellery, cars, whisky or other valuable possessions.
Selling Can Mean Giving Up Future Value
One reason someone may prefer to borrow is that selling locks in today’s price.
Imagine owning an item that has increased significantly in value over several years. If cash is needed for only a few months, selling it means losing any future appreciation as well as the asset itself.
There is no guarantee, of course, that a collectable or luxury item will continue increasing in value. Markets can move in both directions. However, owners may still have reasons for believing that holding the asset makes more sense than disposing of it because of a temporary need for money.
Replacement can also be difficult. Certain watches, vehicles, artworks and collectables may be rare enough that buying an equivalent later would be expensive or impossible.
Selling therefore carries an opportunity cost that is not always obvious from the amount of cash received.
Sometimes the Asset Has Personal Value Too
Not every valuable item is held purely as an investment.
A watch may have been bought to mark a significant achievement. Jewellery can be inherited. A classic car might have taken years to restore. A whisky collection may have been assembled bottle by bottle over decades.
The market can assign a price to those possessions, but that price does not necessarily reflect what they mean to the owner.
If someone knows that their cash requirement is temporary, permanently parting with an important possession may feel unnecessary. Borrowing against the asset can potentially provide another option, although it comes with its own obvious responsibility: the debt must be repaid according to the agreed terms if the owner wants to retain the item.
This is why the decision is not simply financial. It can also be personal.
Why Someone With Wealth Might Need Cash Quickly
There are countless reasons an asset-rich person might need access to money at short notice.
A business owner may see an opportunity to purchase stock at an unusually good price. Someone may need funds while waiting for a property transaction to complete. An investor might want to move quickly on another opportunity without selling an existing holding. There can also be unexpected personal expenses where timing matters more than long-term affordability.
In these situations, the problem is often not lack of wealth but timing.
Selling an asset may take longer than expected, particularly if achieving a fair price matters. Rare or specialist items generally require the right buyer, and rushing a sale can lead to accepting considerably less than the asset might otherwise achieve.
Borrowing can bridge that timing gap when the owner expects other funds to become available later.
Borrowing Is Not Automatically the Smarter Choice
There is an important counterpoint: retaining an asset is not always worth the cost of borrowing.
Loans involve interest and may include fees. If the asset is not particularly important to the owner, selling it could be much simpler. Someone who has an unused luxury watch sitting in a drawer and no desire to keep it may reasonably decide that selling makes more financial sense than paying interest to borrow against it.
The decision therefore depends on several questions:
- How important is the asset to the owner?
- Is the need for cash temporary or permanent?
- How confident is the borrower that repayment can be made?
- What is the total cost of the loan?
- Could another form of finance be cheaper?
- Would selling the asset now mean accepting an unnecessarily low price?
These considerations matter much more than the simple fact that borrowing is available.
The Risk Should Never Be Ignored
Asset-backed lending comes with one particularly clear risk: the security itself.
If the borrower does not repay according to the agreement, they may ultimately lose the asset. That makes repayment planning essential.
Someone considering this type of finance should understand the interest rate, fees, term, valuation process and consequences of missed repayment before entering into an agreement. The emotional value of an asset should arguably make this assessment even more important. Borrowing against a replaceable investment is one thing; borrowing against an inherited item with significant sentimental importance is another.
The ability to raise money against something valuable should never be confused with an obligation to do so.
Wealth Is Often Tied Up
The wider lesson is that personal wealth can exist in many different forms.
Property, businesses, investments, collectables, vehicles and jewellery can all contribute to someone’s net worth, but they are not necessarily convenient sources of everyday cash. Converting those holdings into money often requires time or an irreversible sale.
That explains why borrowing among wealthy or asset-rich individuals is not as contradictory as it first appears.
The decision can simply be about preserving ownership while solving a temporary liquidity problem. If a person believes the asset is worth keeping and has a credible way to repay the finance, borrowing may offer greater flexibility than selling.
Equally, where repayment would be uncertain or the asset no longer serves a useful purpose, selling may be the cleaner option.
Having valuable possessions does not eliminate the need for financial planning. In some respects, it simply changes the choices available. The important distinction is between needing money permanently and needing access to money for a limited period. Once that difference is recognised, the logic behind borrowing rather than selling becomes much easier to understand.