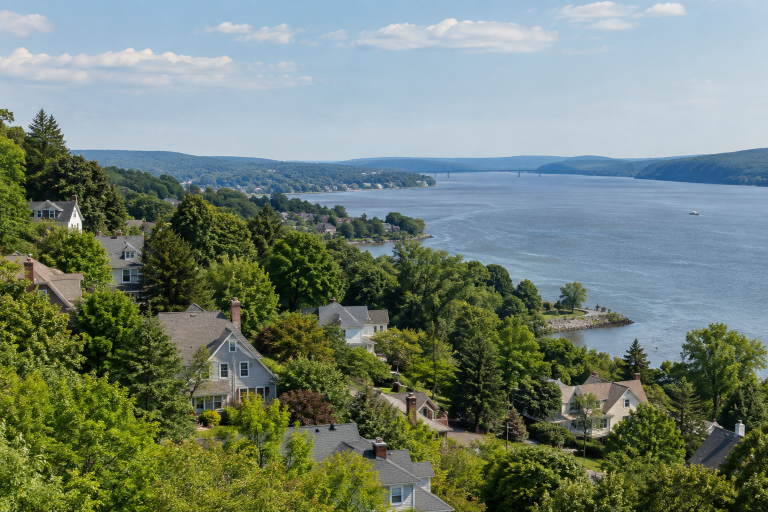
Croton-on-Hudson offers a distinctive Hudson River setting, access to outdoor space, and commuter connections that appeal to buyers seeking a different daily rhythm from the city. Still, a view of the river or a charming older home should be the beginning of the research process, not the end. For an initial look at property types and local lifestyle considerations, Croton-on-Hudson, NY Homes for Sale is a neighborhood guide from The Nancy Kennedy Team, a Croton-on-Hudson real estate team serving buyers and sellers in Westchester County. Its local listings and community overview can help buyers frame a search, but each address deserves its own careful review before an offer is made.
Table of Contents
- 1 Test the Commute in Real Conditions
- 2 Separate Waterfront Appeal From Waterfront Risk
- 3 Review Age, Construction, and Maintenance
- 4 Calculate the Full Monthly Cost
- 5 Confirm Schools and Local Services
- 6 Visit the Neighborhood More Than Once
- 7 Match the Home to Your Lifestyle
- 8 Check Zoning, Easements, and Future Plans
- 9 Use Listing Data Carefully
- 10 Build a Due Diligence Timeline
- 11 Common Buyer Questions
- 12 Let the Checklist Lead
- 13 Conclusion
Test the Commute in Real Conditions
A train schedule and a map estimate cannot fully describe a weekday commute. Make at least one trial trip during the morning period you expect to travel and, if possible, return during the evening rush. Include the walk or drive to the station, parking time, waiting time, the rail trip, and the final leg to work. Review Metro-North service information for Hudson Line schedules, service notices, and station details. Also consider late-night and weekend service, as well as your backup plan when weather, traffic, or a service disruption changes the routine.
Separate Waterfront Appeal From Waterfront Risk
Croton-on-Hudson sits near the Hudson and Croton Rivers, so topography and proximity to water can vary substantially from one property to the next. A water view does not automatically mean direct access, private shoreline rights, or the same insurance needs as another home nearby. Before the inspection deadline, verify the property’s flood zone designation, ask about prior water intrusion, inspect basement walls and floors for moisture indicators, and assess drainage across the lot. FEMA’s Flood Map Service Center can help buyers begin reviewing mapped flood-hazard information. An insurance professional can explain the coverage and pricing available for the specific property.
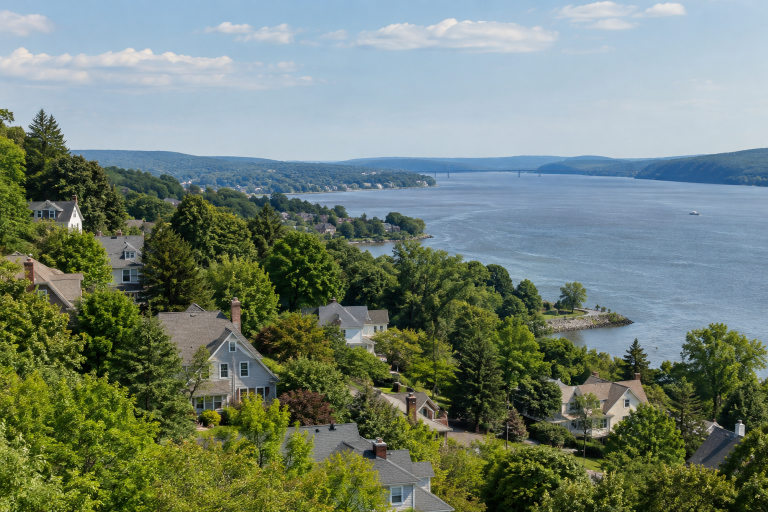
Review Age, Construction, and Maintenance
Older homes can offer mature landscaping, established neighborhoods, and architectural character. They may also have systems that require closer attention. Ask for the age and condition of the roof, electrical panel, plumbing, heating and cooling equipment, windows, insulation, and foundation. Review available permits and renovation records. If the inspection raises concerns, bring in an appropriately qualified specialist for issues involving chimneys, structural movement, septic systems, water quality, environmental conditions, or drainage. A renovation budget should include room for surprises rather than relying only on cosmetic estimates.
Calculate the Full Monthly Cost
The listing price is only one part of affordability. Compare the anticipated monthly costs for each home, including mortgage principal and interest, property taxes, homeowners’ insurance, utilities, maintenance, commuting, parking, association dues, and any flood insurance that may be required or advisable.
A Simple Comparison
- A lower-priced house may need a roof, heating upgrade, or drainage work soon after closing.
- A condominium may have lower exterior maintenance responsibilities, but higher monthly dues and potential assessments.
- A home closer to the station may reduce driving and parking costs, while a more remote property may require a larger transportation budget.
Request the information needed to make a realistic comparison, including tax records, utility history when available, association documents, and insurance quotes.
Confirm Schools and Local Services
Buyers should confirm the school assignment for the exact address, rather than relying on a listing description or a general village label. Check district enrollment procedures, transportation policies, calendars, and programs directly with the appropriate school district. Even buyers without school-age children may view district boundaries as a resale consideration. Also evaluate practical services that shape daily life: grocery access, medical care, childcare, library programs, recreation facilities, parks, and the route to the places you expect to visit most often.
Visit the Neighborhood More Than Once
A quiet showing can hide the everyday pattern of a street. Visit on a weekday morning, weekday evening, and weekend. Listen for train, highway, construction, or neighborhood noise. Look at parking availability, lighting, road conditions, pedestrian routes, and the steepness of driveways or sidewalks. If walkability matters, walk the actual route from the property to the station, the village center, the school, or the park. The experience will reveal details that do not appear in photos, including hills, crossings, weather conditions, and the actual time the trip takes.
Match the Home to Your Lifestyle
Write down your five most important needs before touring. A daily commuter may prioritize access to the station. A remote worker may need a quiet office and dependable internet options. A household with children may value storage, outdoor space, and practical room layouts. A downsizer may prefer one-level living and lower exterior maintenance. This exercise helps separate essential features from attractive extras. It also makes it easier to compare a river-view home, a village property, and a more private hillside setting on the factors that will matter after closing.
Check Zoning, Easements, and Future Plans
Before committing to a property, review what you can change and what may be restricted. Confirm zoning, setbacks, shared-driveway arrangements, utility easements, conservation limitations, and rules affecting additions, fences, decks, pools, accessory structures, or accessory dwelling units. Check municipal agendas and planning materials for nearby projects, roadwork, or proposed developments. New investment can add homes, services, or infrastructure, but construction and changing traffic patterns may also affect the immediate area.
Use Listing Data Carefully
Online listings are useful for spotting patterns, but they rarely tell the whole story. Compare recent sales with attention to condition, lot size, renovation level, location, taxes, water exposure, and distance to transportation. A similar square-footage figure does not make two properties equivalent.
Build a Due Diligence Timeline
- Set a purchase budget and obtain financing approval or verify available funds.
- Tour several areas and test the commute.
- Review flood, insurance, tax, and association information.
- Make an offer with appropriate contingencies.
- Complete inspections, title review, survey review, and permit research.
- Confirm financing and insurance before contingency deadlines.
- Conduct a final walkthrough before closing.
Common Buyer Questions
Are riverfront homes always more expensive?
No. Value depends on the individual location, condition, lot, views, access, taxes, insurance, and buyer demand. A partial view and direct waterfront are not interchangeable features.
Should buyers avoid homes near water?
No. Buyers should evaluate the specific property, including mapped flood risk, elevation, drainage, construction, insurance options, and known history of water damage.
Let the Checklist Lead
Buying in Croton-on-Hudson can mean balancing scenery, outdoor access, and commuter convenience with the practical realities of property condition, insurance, taxes, and everyday travel. The strongest decision is not simply the home that photographs best. It is the one that fits your routine, budget, and long-term plans with confidence.
Conclusion
Buying a home in Croton-on-Hudson involves more than choosing a property with a river view or appealing neighborhood character. Buyers should consider how the location fits their commute, daily routine, budget, and long-term plans. Testing the commute, reviewing flood exposure, checking major systems, and understanding taxes, insurance, and maintenance costs can provide a clearer picture of what ownership may involve. It is also important to visit the neighborhood at different times and confirm details such as school assignments, local services, zoning, and easements for the specific address. Online listings and neighborhood guides can help narrow a search, but they cannot replace property-specific research. By approaching each home with a practical checklist and allowing enough time for due diligence, buyers can make a more informed decision about whether a Croton-on-Hudson property suits their needs.